
Most market analysis in multifamily begins with a familiar premise: identify where growth is strongest and position capital accordingly.
While directionally useful, that approach tends to overweight expansion and underweight durability.
Not all environments reward the same strategies.
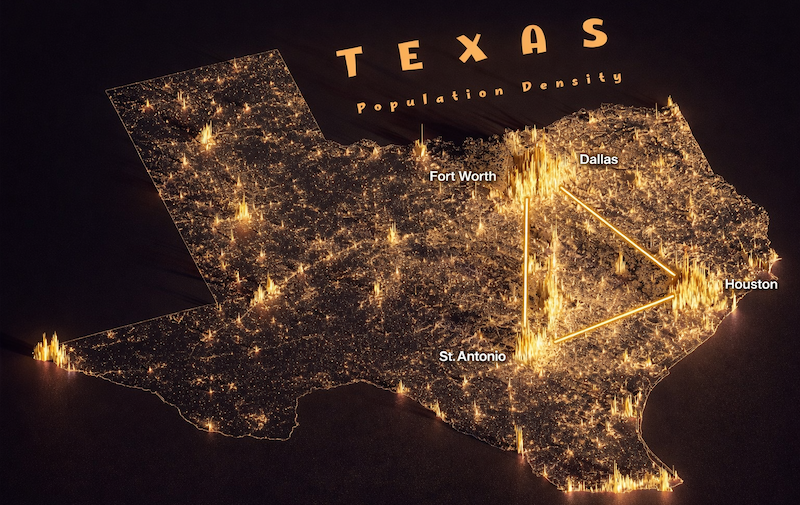
Within the Texas Triangle, Houston workforce housing presents a distinct case. Not because it offers the highest projected growth, but because its underlying structure is more resistant to disruption.
Houston absorbs volatility differently than most markets.
Over the past cycle, capital has flowed disproportionately into higher-end multifamily development across major Texas metros. Dallas and Austin, in particular, have seen significant expansion of Class A inventory, often supported by low-cost debt and favorable capital markets.
Houston participated in this trend, but its composition evolved differently.
A larger portion of its housing stock—particularly in the workforce segment—remains tied to affordability-driven demand rather than discretionary consumption. At the same time, construction costs have increased materially across all markets, raising the replacement cost of new supply.
This creates an asymmetry.
When the cost to build exceeds the cost to acquire existing assets, new supply becomes economically constrained. Existing properties, particularly those positioned below replacement cost, begin to anchor around a basis that is difficult to replicate.
Demand in workforce housing reinforces this dynamic.
Houston’s economic structure supports this segment. The market is not dependent on a single industry. Energy, healthcare, logistics, and international trade each contribute to employment and population stability.
These dynamics are explored in more detail in our investor briefings.
As capital conditions shift, these structural characteristics become more visible.
A significant portion of multifamily assets acquired over the past cycle were structured under fundamentally different capital conditions.
As those structures reset, ownership and pricing are beginning to adjust—often independent of property-level performance.
Once capital conditions shift, outcomes begin to move before it becomes widely recognized.
Debt is more expensive. Proceeds are lower. Equity requirements have increased. These changes affect how new projects are financed and, in many cases, whether they are pursued at all.
At the same time, replacement cost has not reset at the same pace. This reinforces the positioning of existing assets acquired below replacement cost.
This is where structure—not projection—begins to determine outcomes.
Our approach is built around reducing dependency on variables we do not control.
This creates an advantage in environments where costs are unstable, capital is constrained, and execution timelines extend.
In these conditions, outcomes are less dependent on projections and more dependent on structure and operational control.
This framework is applied consistently across opportunities, allowing for repeatable decision-making rather than one-off outcomes. See how this connects to our Investment Framework.
Investors participate as capital partners within a structured operating model, where outcomes are driven by execution and aligned decision-making.
Growth can enhance returns. Structure determines whether they hold.
CONTEXT
These concepts are interdependent. Evaluating them in isolation often leads to incomplete conclusions.